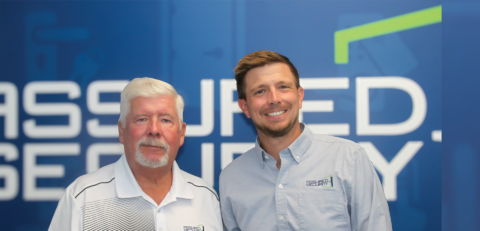
How Jim Fingerman moved his business and then his personal banking to Scale Bank
How Jim Fingerman moved his business and then his personal banking to Scale Bank
Jim Fingerman started working in the family dry cleaning business when he was ten years old. He did what needed doing and never particularly planned on making it his career. Three decades of ownership later, he’s the third generation running Iron Tortoise and Pilgrim Cleaners locations across the Twin Cities.
“I got comfortable and familiar with it,” he says. “You do what you know.”
What he knows is an industry that has been reinventing itself for forty years. Suits, shirts, and ties gave way to more women’s clothing. Then, workplaces got more casual. Smoking bans in public places took another bite. Minnesota once had roughly 300 operating dry cleaning plants; today there are around 45. COVID was, in Jim’s words, close to a final blow—but also an opening—for him.
“The operators who innovated and diversified are the ones still here,” he says. Consolidation was coming, and Jim knew every player in the market. He knew who held assets that could fit into a bigger picture. Bringing that vision to life required a bank that understood the opportunity and could help him act on it.
“The first bank that really gets it”
Scale Bank is the fifth bank Jim has worked with since taking over the company. He’d heard good things about the bank for years. He and Dave Hart, his banker at Scale, met well before there was any business to do.
What made the earlier banking relationships wear thin wasn’t necessarily a single bad experience; it was the feeling of not quite mattering.
“I wasn’t huge, and I wasn’t small,” Jim says. “It didn’t seem to matter much to them either way.” Banker turnover meant a new contact every so often and the same conversation: explaining his business, his industry, and his plans to someone who’d be gone in eighteen months.
Unwinding a long-standing banking relationship which included lines of credit, checking accounts, and ACH wires is complicated, and Jim had a business to run in the meantime. When he was ready, in August 2025, the difference showed up immediately in the kind of questions Scale asked.
“Scale is the first bank that really gets it,” Jim says. “They were interested in the story. They wanted to hear what my situation actually was instead of putting me in a box. They heard what was going on inside the company and wanted to dig in and find something that worked for both of us.”
Scale moved the business checking and money market accounts across all locations and helped finance real estate. Dave worked alongside Jim and his fractional CFO, Steve Klein, through the whole transition.
“Steve is very detailed, and everyone worked together,” Jim says. “It couldn’t have gone more smoothly. Everything was laid out. Sign here, and it’ll be taken care of.”
The quarters
Dry cleaning locations need quarters. Customers come in specifically for change, and the change machines have to be full. Jim’s stores go through them in bulk. Every other bank sent quarters the standard way: rolled. Which meant Jim’s staff spent part of their week breaking open rolls of quarters, one at a time, so the machines could be filled.
Scale holds unrolled quarters for him instead. Now, the tellers ask whether he needs any every time he comes in. It’s exactly the sort of thing a bank only fixes if someone has bothered to understand how the business actually runs day to day.
Then came the part he never expected
Moving personal banking to a commercial bank went against everything Jim had believed about how to manage his finances.
“I always thought it created a vulnerability,” he says. “I firmly believed in keeping things separate.”
Two things changed his mind. The first was simply how good the business relationship had been. The second was friction. With multiple banking relationships, moving money around was harder than it needed to be.
“Doing business with Scale has been such a wonderful experience,” he says. “Having it all in one place has been a blessing and a stress relief. Seamless. They took care of what I needed. Scale is big enough to be useful and relationship-oriented to know you and know your situation. You’re not getting someone disconnected who’s only looking at numbers. It’s personal and hands-on.”
One banker, the whole picture
Dave is now Jim’s primary banker for both the business and his household finances. That came into play recently as Jim and his wife took on a significant renovation of their home. Because Dave already understood Jim’s full financial picture including the businesses, the real estate, the personal balance sheet, there was no need to start from scratch. Scale had already established a home equity line for him and was able to expand it to fit the size of the project.
“Dave makes problems go away,” Jim says. “He has an understanding of the bigger picture. It made it seamless to pursue the project.”
“Never been treated like this”
Ask Jim what surprised him, and he doesn’t mention a product.
He says, “There’s a very genuine vibe that comes out of that bank. Every single person is appreciative, grateful, helpful, committed. Scale Bank is a real financial partner; they are not just transactional. I’ve never been treated like this. It’s so different.”
Part of that security, he says, comes from knowing what Scale is and isn’t building toward. Scale isn’t positioning itself to be sold or acquired, which means the banker Jim has today is the banker he’ll have next year. A trusted colleague of his has banked with Scale for years and told him the same thing.
“I honestly can’t thank them enough for the level of interest they’ve shown in me,” Jim says. “I love doing business with Scale Bank.” He doesn’t see himself making another change.
Considering the same move?
If Scale Bank already handles your business banking, there’s a good chance we can simplify the personal side too with checking, savings, home equity lines, and mortgage financing, with the same banker who already knows your business.
The advantage is more than convenience. It’s knowing that when an opportunity or a big decision shows up, your banker already has the context to move on it with you.
Media Contact: Katy Sullivan
Katy Sullivan is the Media Contact for Scale Bank and Principal of Substance & Sums Communications. A strategic communications leader and Prosci® Certified Change Practitioner, she helps organizations build reputation, raise awareness, and tell impactful stories through thoughtful media and employee engagement strategies.